
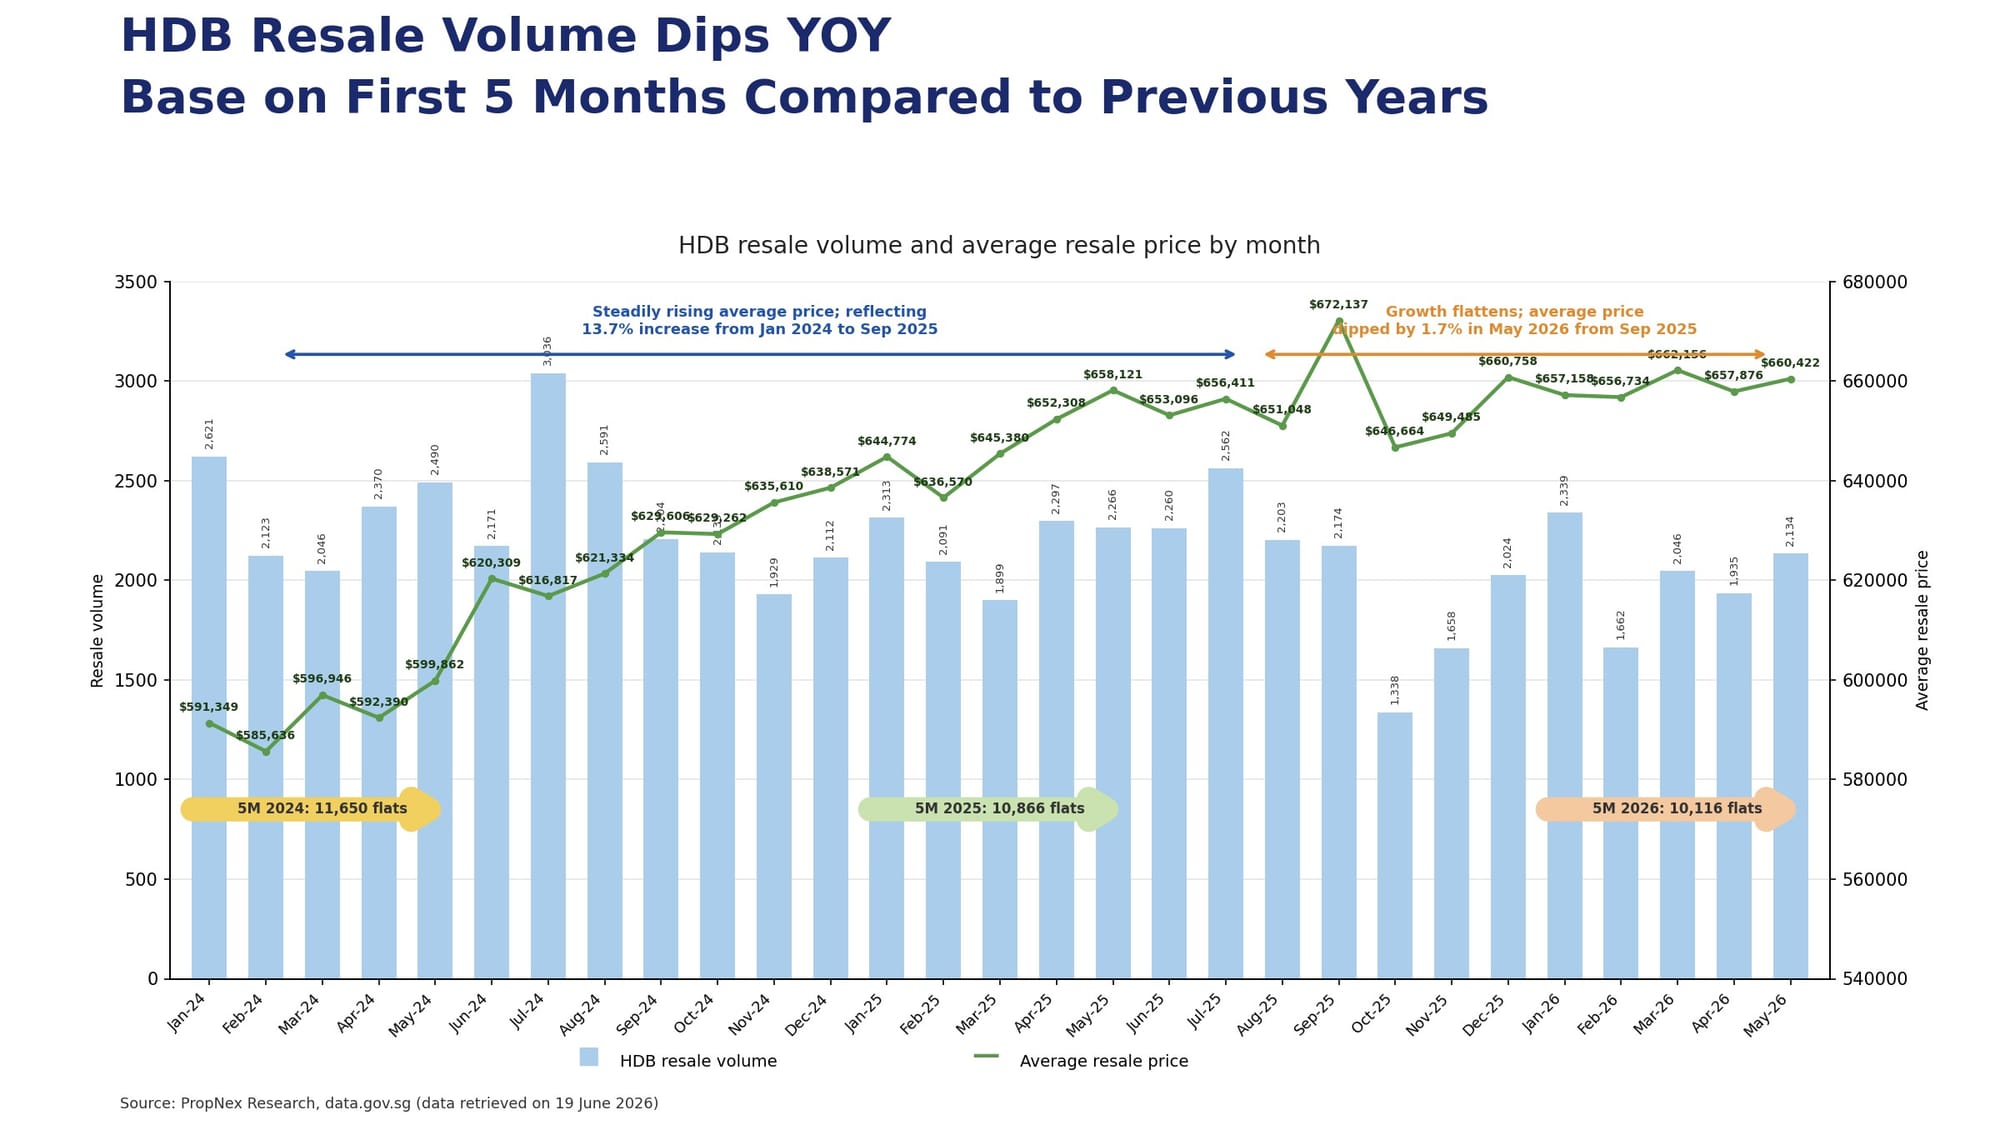



Consider Mdm Wong, an illustrative owner aged 67, not a real client. She bought her 4-room flat in Toa Payoh in 1990 for $95,000. It is worth about $750,000 today. Her children have moved out. She has been thinking about selling "when the time is right" for four years now. Every year she reads about million-dollar HDB transactions and tells herself she is fine. The market is still good. What she does not know is that her flat has 54 years of remaining lease. A 35-year-old couple buying her flat today can only use $436,500 in CPF. Not the full valuation. They need to make up the difference in cash. The pool of buyers who can comfortably afford her flat at full price is already smaller than it was three years ago. In three more years, it will be smaller still. The cliff is not the lease running out. The cliff is the buyer pool shrinking. Quietly, incrementally, invisibly. Until the day Mdm Wong lists her flat and finds out she has fewer bidders than she expected. This article is what she needs to know before that day arrives.
Most HDB owners know their flat is on a 99-year lease. Almost none of them know that 55 years remaining is where the financing cliff begins, where CPF usage gets pro-rated, bank loan tenures start shortening, and monthly instalments rise for your buyer.
The cliff does not announce itself. You do not feel it in your property tax. You do not see it in your agent's listing price. You feel it the day you get fewer offers than you expected. And your agent quietly suggests dropping the asking price.
This is what's actually happening, and how long you have to plan around it.
The Financing Cliff: What Actually Happens at 55, 50 and 30 Years
There are two separate mechanisms that interact with your flat's remaining lease, CPF pro-ration rules and MAS bank loan tenure caps. Both tighten as the lease shortens. Neither tightens gradually. They tighten in steps, and each step silently removes a portion of your buyer pool.
Full CPF OA usage is only permitted if the remaining lease covers the youngest buyer to age 95. This means: buyer's current age + remaining lease must equal at least 95.
So a 35-year-old buying your flat needs at least 60 years of remaining lease for full CPF access (35 + 60 = 95). At 55 years remaining, a 35-year-old buyer gets pro-rated CPF. Not the full amount. They must make up the shortfall in cash.
Every cash shortfall makes your flat harder to buy. And the buyers who can't make up the cash shortfall simply do not make an offer.
MAS caps bank loan tenure at the lower of 30 years and (remaining lease minus 30 years). At 55 years remaining, maximum loan tenure is 25 years. Not 30. At 50 years, maximum is 20 years. At 45 years, maximum is 15 years.
A shorter loan tenure means higher monthly repayments on the same loan amount. Higher monthly repayments mean a buyer needs a higher income to clear TDSR. Fewer households qualify. Your buyer pool shrinks.
The Numbers at Every Threshold: All in One Place
What Your Flat Is Worth Today: Bala's Table Made Simple
Bala's Table is the Singapore Land Authority's official leasehold value table, the formula valuers use to measure how much value a shorter lease takes off. This is what it says about flats with 40 to 99 years left.
Bala's Table: Value Retained vs Fresh 99yr LeaseWhat the Cliff Costs Your Actual Buyer: Two Real Scenarios
This is what a 35-year-old couple faces when buying Mdm Wong's $750,000 Toa Payoh flat with 54 years left, compared with a flat at the same price with 70 years left.
The same flat. The same price. But Mdm Wong's buyer needs $168,000 more in cash and must earn $1,300 more per month just to qualify. That is the cliff. Mdm Wong does not pay the price for this directly. But her buyer does. And when buyers struggle to pay, they either negotiate harder or walk away.
The Sell Window: Which Estates Are Affected Right Now in 2026
Flats built in the late 1970s and early 1980s are approaching or have already crossed the 55-year threshold. Here is the estate-level picture.
Sell Now, Hold, or Upgrade: The Honest Framework
✅ The Case For Acting Now
- Your flat is already below 60 years remaining: CPF pro-ration is either active or approaching for most buyer profiles
- Your estate has 1,000+ newly MOP-ed flats coming onto the market in 2026, in Queenstown, Toa Payoh or AMK, adding direct competition
- You have a clear upgrade target: the proceeds model works and a suitable new launch is available now
- Your children have moved out and you're keeping up a big flat you no longer need, so the lifestyle case for right-sizing is already there
- Private prices rose 0.9% in Q1 2026 while HDB prices dipped, so the gap between your flat and your upgrade target is widening
❌ The Case For Waiting
- Your flat is above 65 years remaining: you are still in the full-pool, full-CPF zone and the urgency is lower
- Your school zone is actively working for you: children still in the 1km ballot cycle and you need the address
- You have no upgrade plan yet. Selling into a private market you can't afford or haven't researched is worse than holding
- Your flat is truly exceptional, with a high floor, open views or a recent renovation, and premium buyers are still paying for that
What You Can Access If You Act Now: The New Launch Option
For a Toa Payoh or Queenstown flat owner with 54 years of lease remaining, the decision to sell and upgrade is not just about avoiding the cliff on exit. It is about getting a fresh 99-year lease for your next 20 years of ownership. And everything that comes with it.
Your buyer in 2046 faces zero cliff
only property: no stamp duty
Every sqft you pay for is liveable
For a Queenstown seller with $750,000 proceeds and $550,000 CPF OA (post-refund), the entry point for a 2BR at Parcel A (~$2,503 psf, est. $1.7M for ~680 sqft) is within reach with a moderate mortgage. A 3BR at Thomson Reserve (~$2.68M) requires a stretch. But the income threshold at $21,000 to $26,000/month household is achievable for many dual-income couples in their mid-50s and early-60s who have spent decades building careers and CPF savings.
+ What Ten Years Managing MCSTs Taught Me About Ageing Flats →− Collapse
In my decade of managing MCST operations across estates of every age and type, the ageing flat problem is the one most owners understand the least. Not because they are not intelligent, but because the consequences are invisible until they are not. You do not feel your buyer pool shrinking. You do not get a notification when a 35-year-old couple decides not to view your flat because the CPF calculator showed them they need too much cash. You find out at the negotiation table, months after you listed.
The most common thing I hear when I walk through this with clients is: "Why didn't anyone tell me this 5 years ago?" The honest answer is that most agents either do not know the mechanics in detail, or they don't want to complicate the sales conversation. I would rather tell you now.
+ The 55-Year Threshold, By Build Decade →− Collapse
The 55-year threshold is real, it is measurable, and it is predictable. If your flat was built in the early 1980s, you are at or near it right now. If it was built in the mid-1970s, you have already crossed it. The Bala curve and the CPF pro-ration rules are not opinions. They are the official formulas that every bank and every CPF officer applies to your buyer's application.
+ Why Waiting Past 60 Years Remaining Costs You Buyers →− Collapse
My practical advice: if your flat has fewer than 60 years remaining and you are thinking about selling in the next 3 to 5 years, there is no strategic reason to wait. The buyer pool at 60 years is better than at 55, better than at 50, and materially better than at 45. You do not have to rush. But you should stop telling yourself there is no urgency. Because the data says otherwise.
Your situation is different. Get it in writing.
I'll work through your budget, loan, options and exit in a free written Property Decision Review. No obligation.
Get my free Property Decision Review →Sources+ Show →− Hide
Singapore Property Research Hub, Lease Decay in Singapore: What Changes at 60 and 30 Years Remaining · sg.properties, September 2025
CheckHowMuch.sg, How Much Does Your HDB Lose in Value Each Year? Bala's Table analysis of 9,701 HDB blocks · April 2026
Let's Talk Property, HDB Lease Decay: How a HDB Flat Might Depreciate Over Time · letstalkproperty.sg
SingaporeHomeValue.com, Lease Decay: How It Impacts Your HDB Flat's Value · October 2025
PropertyGuru, CPF and HDB Loan New Rules: How Much Can You Use? · propertyguru.com.sg
CPF Board: CPF Housing Usage Rules · remaining lease coverage to age 95 requirement
MAS: Housing Loan Regulations · bank loan tenure caps by remaining lease
Singapore Land Authority: Bala's Table leasehold relativity model · official SLA formula
HDB: Resale Portal · flat lease information available via HDB Map Services
mychoicehomez.com, Lease Decay Singapore 2026: What Every Owner Must Know · April 2026
This article is for informational and educational purposes only. It does not constitute financial, investment, or legal advice. Property investments involve risk. Past performance is not indicative of future results. Readers should seek independent advice from licensed professionals before making any property or financial decision. James Ong is a licensed real estate salesperson (CEA Reg No. R008385F) with PropNex Realty Pte Ltd and is not a licensed financial adviser.
Member discussion