
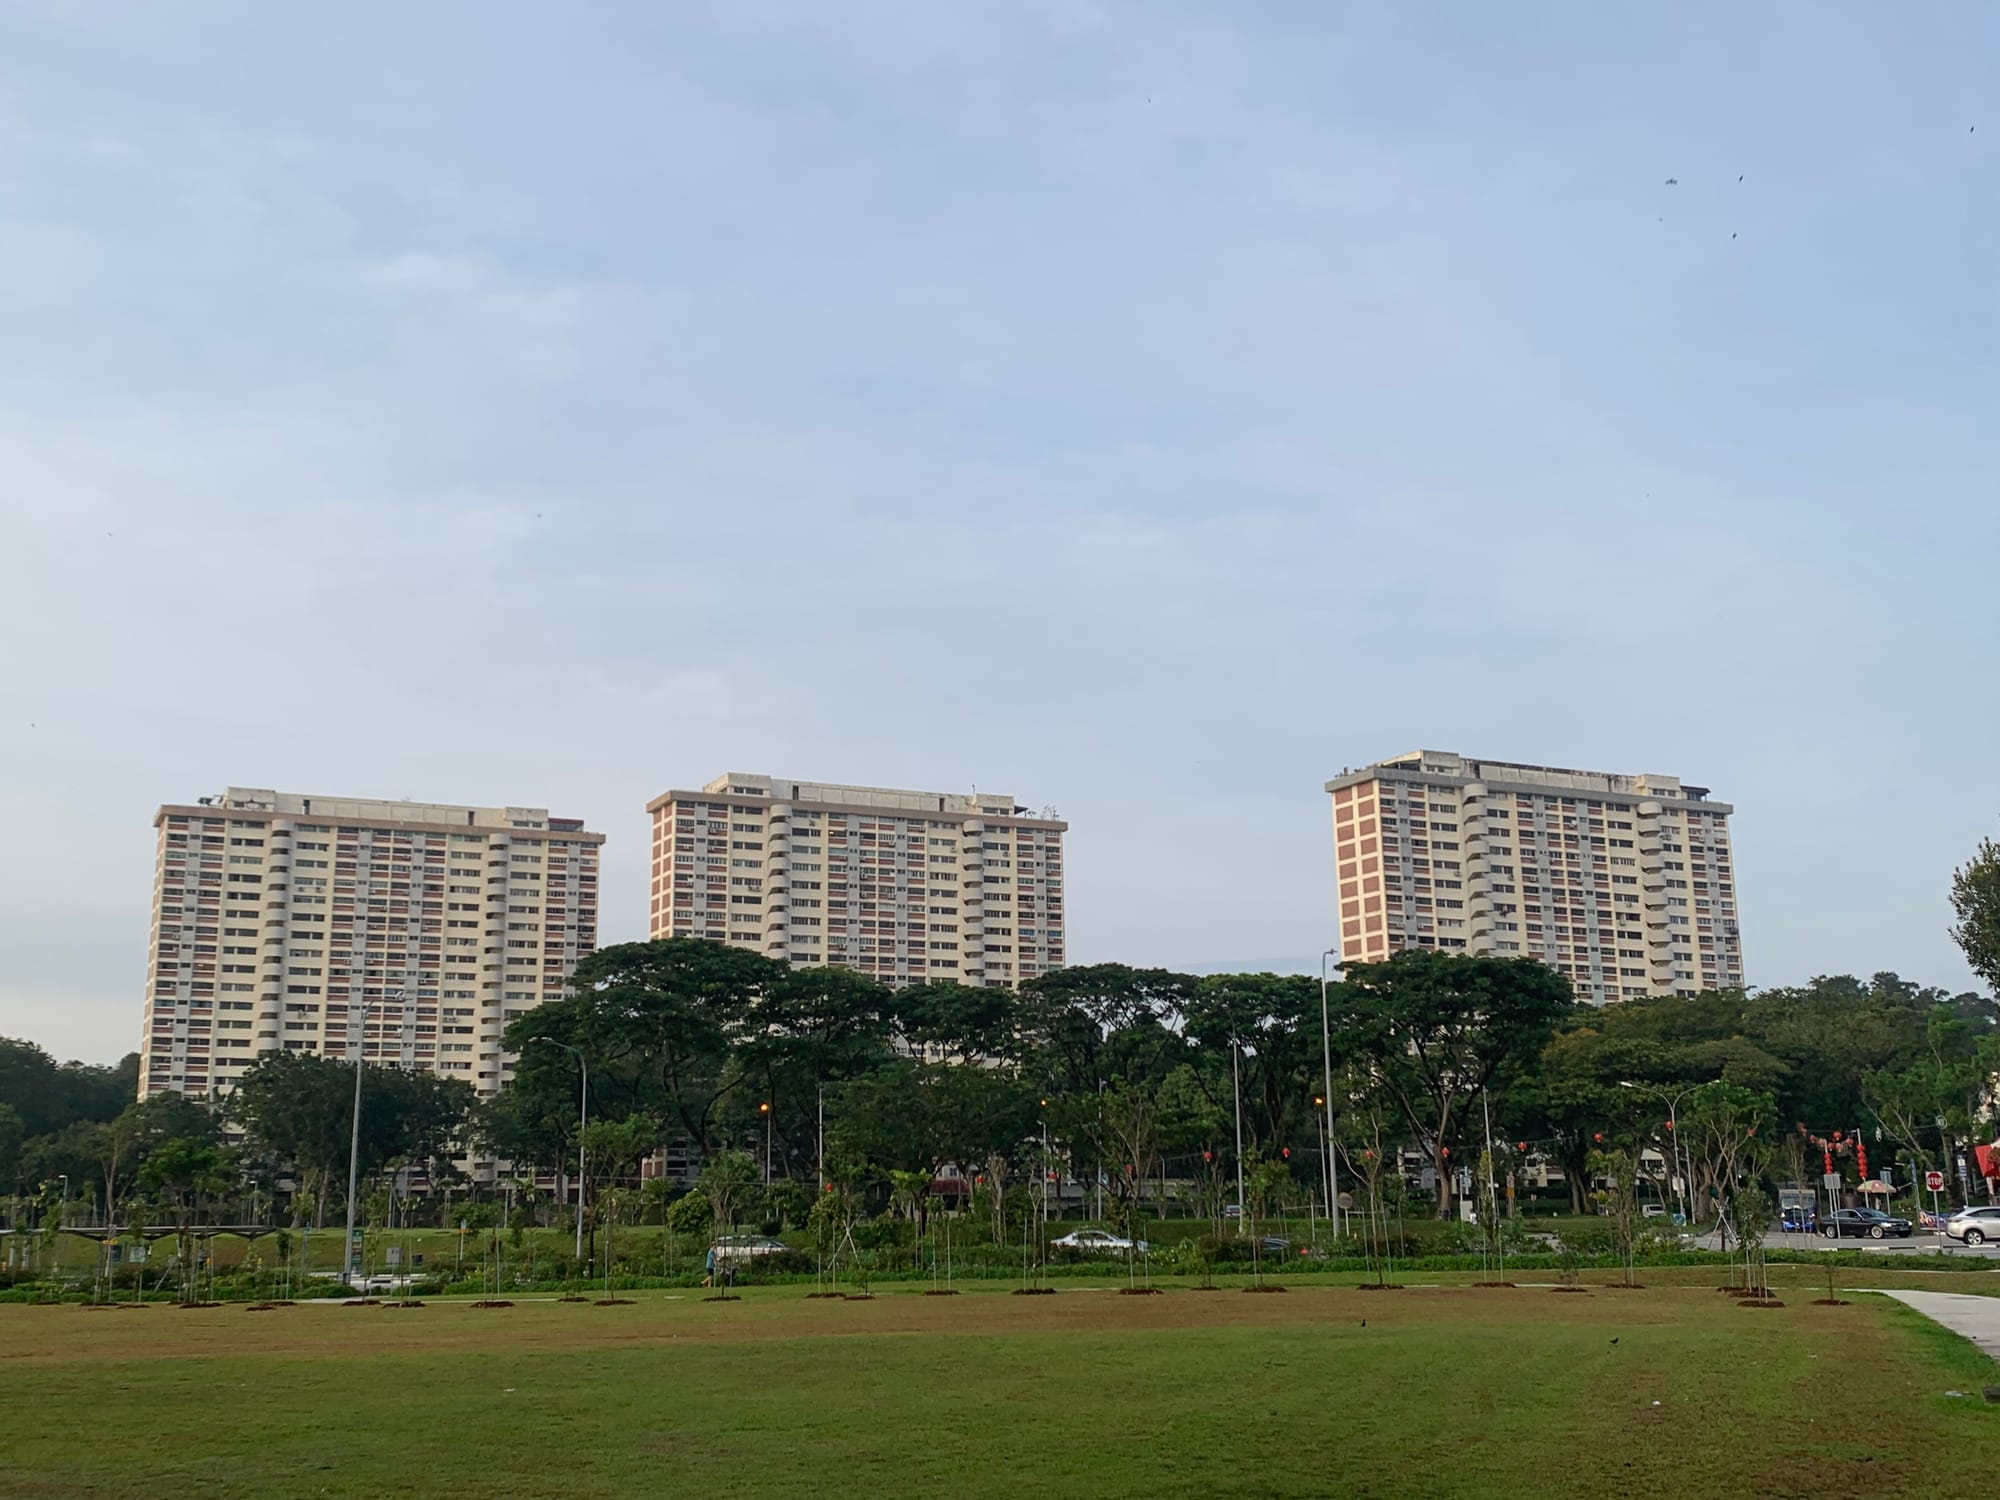



MCST Governance: 45-Year Infrastructure Is Not a Minor Point
Braddell View was completed in 1981 and Lakeview in 1977. At 45 to 49 years old, their major building systems, lifts, water tanks, electrical risers, waterproofing and facade, are at or past their normal design life. What this means in practice: MCST sinking fund drawdowns are accelerating, and special levies are a recurring feature rather than an exception. Before entering either estate as a resale buyer, the three checks that matter most:
1. Sinking fund balance and 5-year projection. Ask the agent for the MCST financial statements from the last AGM. Divide the sinking fund balance by the number of units. A healthy reserve for a 45-year-old estate is $30,000 to $50,000 per unit in the sinking fund. Below that, a special levy is likely within 3 to 5 years.
2. Outstanding or pending major works. Request the AGM minutes from the last two years. Look for deferred lift replacement, waterproofing failures, water tank overhauls, or facade repair proposals that were postponed. These are the levies waiting to be called.
3. Managing agent tenure. A managing agent who has been on site for 3+ years typically has continuity of knowledge about what is deferred. Several managing agent changes in a short time often point to unstable MCST governance, which makes the maintenance backlog worse.
Thomson View Sellers: Net Proceeds Analysis
Thomson View's 255 units sold for $810M in the July 2025 High Court-approved en bloc. Average gross proceeds per unit were approximately $3.18M. But the number that matters for reinvestment is what lands in your account after deductions. For a typical Thomson View owner who purchased in the late 1990s or early 2000s:
| Item | Est. Amount |
|---|---|
|
Gross en bloc proceeds (avg, 255 units)
$810M ÷ 255 units
|
~$3,176,000 |
|
Less: Legal fees (conveyancing, en bloc solicitor)
Approx $5,000 to $12,000 per unit
|
−~$8,000 |
|
Less: CPF OA refund + accrued interest ⚠️
CPF withdrawn × 2.5%/yr compounded from date of first use. Example: $500K of CPF used in 2000 → about $425K of accrued interest over 25 years → a total CPF refund of about $925K. This goes back to your OA and can be used for the next purchase.
|
−$TBC (individual) |
|
Less: Outstanding mortgage (if any)
Fully paid for most long-term owners
|
−$0 (assumed cleared) |
| Estimated net cash in hand (excl. CPF refund to OA) | ~$1.5M to $2.5M |
| ⚠️ CPF accrued interest is the number most Thomson View sellers underestimate. The refund goes back to your OA and can be used for the next purchase, so it isn't lost. But the cash in hand after the CPF refund is very different from the gross sale price. James can model your CPF position before you commit to your next home. | |
For Thomson View sellers considering Thomson Reserve: The CPF OA refund from the en bloc, accrued interest included, can be used for the next property purchase. A seller who refunds about $925K to the OA can use it for the 20% of the downpayment that CPF may cover, and towards the monthly loan. The 5% that must be paid in cash works out to roughly $130,000 to $175,000 for a Thomson Reserve 3BR at an estimated $2,400 to $2,800 psf. Most Thomson View sellers, having held for 20+ years, should be in a strong position to reinvest, as long as they've modelled their CPF position properly.
Why the En Bloc Is Still Not Coming for Braddell View
The same three structural barriers from 2019 are unchanged in 2026.
GLS competition. Thomson View sold at $1,178 psf ppr. And that was a leasehold estate with demolition and consent complexity. Springleaf Residence's site ($905 psf ppr) was a clean GLS parcel. Upper Thomson Parcel A ($1,062 psf ppr) likewise. Developers consistently prefer the certainty of GLS over the consent and demolition risk of a 918-unit leasehold en bloc. Braddell View's $2.08B reserve price requires a developer to pay more per plot ratio on a 51-year leasehold asset than Thomson View achieved. Plus lease top-up cost, demolition, and the timeline risk of securing 80% consent from 918 households.
The reserve price math. For Braddell View to be commercially viable for a developer at $2.08B, the eventual launch price would need to significantly exceed comparable new launches. In a corridor where Thomson Reserve is expected at $2,400 to $2,800 psf and the GLS land cost is $1,178 psf ppr, a developer paying $2.08B for Braddell View would need to launch at materially higher PSF to make the land cost work. After demolition, lease top-up, and construction. The arithmetic is difficult without a step-change in market pricing that the current cycle does not support.
918-unit consent. Getting 80% consensus across 918 households. With a mix of long-term owners fully paid up, recent buyers who need the premium, investors holding for rental income, and owners who simply do not want to move. Is a structural challenge that does not resolve regardless of market conditions.
Thomson Reserve previews October 2026, 1,268 fresh 99-year units from UOL, CapitaLand, and SingLand, launching into the same District 20 corridor where Braddell View and Lakeview Estate sit with roughly 50 years of lease remaining. If you own either estate, the corridor benchmark just reset: your future buyers will now compare your pre-harmonisation asset against a new development at an estimated $2,400 to $2,800 psf with a full century of lease. This is the honest picture. The lease-decay math, the Thomson View seller's net-proceeds reality, and what the new launch calendar means for your specific position.
Braddell View and Lakeview Estate have genuine strengths: Singapore's strongest school cluster in D20, three MRT lines, and large units that are hard to find at $1,000 to $1,100 psf. As investment assets, the lease-decay curve is accelerating. Below 50 years remaining, CPF usage tapers and bank financing constrains your future buyer. Thomson Reserve's October 2026 launch is the single most important event this corridor has seen since Springleaf Residence launched at $2,175 psf. This article maps what it means for owners, buyers, and Thomson View sellers reinvesting their proceeds.
Move 1: The Case for Braddell View and Lakeview
The standard case for both estates is real, and it is worth stating clearly before addressing what the market tends to gloss over.
School zone. Raffles Institution sits approximately 1.5km from Braddell View. Within the realistic ballot radius for some entry blocks. Catholic High School is nearby. Ai Tong School (1km) is confirmed within Thomson Reserve's zone, which is 400 metres from Lakeview. For families with children approaching Primary 1, this corridor carries a school-zone premium that has persisted across cycles. It is the single strongest structural argument for entry.
Transport. Braddell MRT (NSL) is approximately a 5-minute walk from Braddell View. Caldecott MRT (CCL + TEL interchange) is accessible from the southern end of both estates. Lakeview sits closer to Upper Thomson TEL. Three MRT lines across two estates is connectivity that most Singapore developments cannot match. Bright Hill CRL interchange is projected for 2030, adding a fourth line to the corridor.
Space and value. At $1,000 to $1,100 psf, Braddell View offers 4-bedroom units in the $1.4 to 1.6M range. A price point that has effectively vanished from new launches in D20. JadeScape's equivalent unit type now transacts at $2.2M+. Lakeview's 240 units are similarly sized. For own-stay buyers who need space and want an established mature neighbourhood, MacRitchie Reservoir, Thomson Plaza, Bishan-AMK Park. The case is not illusory.
Rental yield. Both estates yield an estimated 3.5 to 4.0% on large units, driven by the school-zone premium on the tenant side. Absolute rents of $4,000 to $5,500/month for a 3 to 4 bedroom unit are achievable in the current market.
| Feature | Braddell View | Lakeview Estate |
|---|---|---|
| Completed | 1981 · ~45 years old | 1977 · ~49 years old |
| Remaining lease (2026) | ~51 years | ~50 years |
| Units | 918 units | 240 units |
| Avg PSF (2026) | $1,001 to $1,108 psf | $991 to $1,164 psf |
| Primary MRT | Braddell (NSL) · Caldecott (CCL+TEL) | Upper Thomson (TEL) · Caldecott (CCL+TEL) |
| En bloc history | 2019 tender: zero bids at the $2.08B reserve | No completed attempt |
| GFA harmonisation | Pre-harmonisation (1981 build) | Pre-harmonisation (1977 build) |
| Nearest new launch | Thomson Reserve, ~400m (Oct 2026) | Thomson Reserve, ~400m (Oct 2026) |
Deep DiveJames's Star Scorecard+ Read →− Collapse
The STAR Score: Honest Entry Rating for 2026
Raffles Institution ~1.5km. Catholic High School. Ai Tong within the corridor. Singapore's strongest D20 school cluster. The single most defensible reason to pay the $1,000 psf premium over equivalent-aged estates elsewhere.
Braddell NSL walkable. Caldecott CCL+TEL interchange accessible. Lakeview: Upper Thomson TEL ~8 min. Three MRT lines across both estates. CTE and PIE. Bright Hill CRL interchange est. 2030 adds further connectivity.
Thomson Reserve (Oct 2026) and Upper Thomson Parcel A (Jan 2027) confirm corridor investment. But each new launch also raises the comparison baseline. The transformation lifts the precinct. And sets a new resale hurdle for ageing assets in the same geography.
Thomson Plaza walkable. Bishan-AMK Park. MacRitchie Reservoir. Junction 8. An established mature neighbourhood with genuine character. Not a new estate waiting for its first retail tenant.
~50yr lease. Decay accelerating. En bloc at $2.08B structurally challenged (same barriers as 2019). Special levies compounding on 45-year infrastructure. Pre-harmonisation GFA means you are paying for strata area that includes AC ledges. The returns trajectory is heading the wrong direction.
STAR Score: 58 / 100, ⭐⭐⭐ Decent
Schools and transport are genuinely excellent. Lease decay and returns trajectory are not. This score reflects entry at current market 2026. Not James's personal assessment of existing owners' situations, which depend on their specific hold horizon and purchase price.
Move 2: The Lease-Decay Reality, the MCST Reality, and the Net-Proceeds Analysis
The mainstream buyer guide for Braddell View covers PSF, school zone, and MRT distance. It consistently omits three things that determine whether your hold position is sustainable: the lease-decay cliff, the MCST governance reality on 45-year infrastructure, and. For Thomson View sellers reinvesting. What the net proceeds actually look like after CPF, legal, and BSD.
Lease Decay: The Financing Cliff Every Buyer Needs to Map
Lease decay is not abstract. It operates through two hard mechanisms, CPF restriction and bank loan tenure cap. That directly constrain your future buyer's ability to finance your property. As those constraints tighten, your buyer pool shrinks and your resale price adjusts accordingly.
| Remaining Lease | CPF Usage | Bank Loan Tenure | Buyer Pool Impact |
|---|---|---|---|
| 60+ years | Full CPF OA usable | Up to 30-year loan | No restriction |
| 50 to 59 years | Pro-rated for buyers aged 36+ | Loan tenure capped (lease − 30yr) | Younger buyers unaffected; 40+ buyers begin to notice |
| 40 to 49 years (Braddell View in ~5 to 11 yrs) | Significantly pro-rated for most buyers | Max loan tenure 10 to 20 years | Higher cash outlay required; pool narrows |
| Below 40 years | CPF OA use effectively unavailable for most | Max loan tenure <15 years | Cash buyers only; pool shrinks substantially |
CPF rule: if remaining lease does not cover the youngest buyer to age 95, CPF OA usage is pro-rated proportionally. Bank loan rule: remaining lease must exceed loan tenure by at least 30 years (HDB) / 20 years (private). Braddell View (~51 yr remaining in 2026) is approaching the point where a 40-year-old buyer needs to verify CPF eligibility. And where Braddell View's 5-year resale buyer (2031, ~46 yr remaining) will face a notably tighter financing environment.
Deep DiveBraddell View vs Lakeview: The Corridor Comparison+ Read →− Collapse
The Corridor at a Glance: How the PSF Stacks Up
| Project | Status | Avg PSF | Gross Yield | Lease |
|---|---|---|---|---|
| Thomson Reserve | Preview Oct 2026 | Est. $2,400 to $2,800 | Est. 2.8 to 3.2% | Fresh 99yr |
| Upper Thomson Parcel A | ~Jan 2027 | Est. ~$2,400+ | Est. 3.0 to 3.2% | Fresh 99yr |
| Springleaf Residence | Launched Aug 2025 | $2,175 (92% sold) | Est. 3.0 to 3.2% | 99yr from 2025 |
| JadeScape | Resale | ~$2,296 | 3.2% | ~97yr left |
| Bishan Park Condo | Resale | ~$1,427 | 2.8% | ~64yr left |
| Braddell View ★ | Resale | ~$1,041 | Est. 3.5 to 4.0% | ~51yr left |
| Lakeview Estate ★ | Resale | ~$1,068 | Est. 3.5 to 4.0% | ~50yr left |
Sources: EdgeProp May 2026 · GuocoLand launch data Aug 2025 · URA GLS Programme 2025. Thomson Reserve PSF is market estimate ahead of October 2026 official pricing. Confirm at showflat preview.
The PSF gap between Braddell View ($1,041) and Thomson Reserve (est. $2,400 to $2,800) is structural, not cyclical. Every new launch at $2,000+ psf resets what your future buyer compares your estate against. And the question they ask themselves about your 50-year lease and 45-year-old infrastructure is the same one they were asking in 2019, just with a higher new-launch reference point alongside it.
A Corridor Decision in 2018: What the Numbers Look Like Eight Years Later
In 2018, a buyer in this corridor faced three options: JadeScape at launch ($1,700 psf, 1,044 sqft, ~$1.77M), Braddell View (~$650 psf, 1,400 sqft, ~$910K), or waiting. The Braddell View case was compelling: more space, less money, and en bloc talk was everywhere. JadeScape launched, 1,044 sqft for $1.77M. Braddell View, 1,400 sqft for $910K. Same corridor. Different asset profiles.
In 2026: JadeScape transacts at approximately $2,296 psf, or ~$2.4M for that same unit. A $630K gain on a 1,044 sqft unit over eight years. Braddell View's 1,400 sqft unit at ~$1,041 psf is approximately $1.46M. Up ~$550K from $910K in 2018. The absolute dollar gain is similar. The per-sqft trajectory is not: JadeScape appreciated from $1,700 to $2,296 psf (+35%). Braddell View from ~$650 to ~$1,041 psf (+60%). But from a much lower base, with 8 fewer years of lease, and against a backdrop of rising financing constraints for the next buyer.
The comparison is not about who made more money on paper. It is about what each asset looks like to the next buyer in 2026, 2030, and 2035. A JadeScape buyer in 2026 is selling into a market with clean 97-year lease, harmonised GFA, and a buyer pool that can use full CPF and secure 30-year loans. A Braddell View seller in 2026 is selling into a market where the buyer's CPF eligibility is entering the pro-ration zone, where Thomson Reserve has just launched 400 metres away at twice the PSF, and where a future seller in 2031 will face the ~46-year lease constraint. These are real differences that compound over time, and they are worth understanding before making the next decision.
Move 3: What the Corridor Looks Like From Here
The property-as-asset case for Braddell View and Lakeview is narrow in 2026. But the own-stay case is not zero. The distinction matters, and the market tends to conflate them.
✅ Entry makes sense if:
- Primary 1 registration in the next 3 to 5 years: Raffles Institution, Ai Tong, Catholic High
- Long own-stay (15+ years) with no reliance on en bloc or capital appreciation
- Large unit requirement that cannot be met at new launch prices in the same corridor
- Zero reliance on bank financing for your future buyer (cash purchase exit plan)
❌ Entry is difficult to justify if:
- Primary investment thesis relies on en bloc (same barriers as 2019)
- 10-year hold targeting capital appreciation: lease decay compounds
- Comparison against Thomson Reserve or Parcel A on yield-adjusted total returns
- Future buyer needs bank financing: tightening tenure constraints narrow pool
For existing owners: The decision is not automatically to sell before Thomson Reserve launches. Thomson Reserve's 3 to 4 year construction period means buying off-plan today and selling Braddell View during the construction window, rather than immediately, is a viable structure for owners who need transition time. What is worth doing now is running the CPF accrued interest calculation, confirming your ABSD position if you are selling your only property, and understanding your net proceeds so you enter the Thomson Reserve showflat with the numbers already done rather than discovering them there.
James's Note
The schools are real. The space is real. The lease-decay math is also real. The question is which of these you are actually buying for.
In my years as a Managing Agent I sat across the table from owners in exactly this position. Good entry decisions on paper, ageing infrastructure they had not paid attention to, and a lease clock running in the background that nobody in the transaction had flagged clearly. The special levies were not surprises to the MCST. They were surprises to the owners, because nobody explained what a 45-year-old building's maintenance trajectory looks like in practice. I am not telling Braddell View or Lakeview owners to do anything specific. That depends entirely on their own timeline, CPF position, and family situation. I am saying that the calculation is worth doing properly, with accurate numbers, before October 2026. After that, the corridor has a new reference point, and every conversation will happen against that backdrop.
Deep DiveFrequently Asked Questions+ Read →− Collapse
Waiting for en bloc has a cost too
Thomson View next door took 17 years and five attempts before its collective sale succeeded at $810 million in 2025. Owners who held on were paid. They also spent those years in an ageing building, paying rising maintenance and special levies, with capital tied up in a lease that kept shortening.
The proposed lower consent thresholds help with the vote, not with the developer's maths: 35% ABSD on the land and a five-year deadline to sell every new unit still decide whether a bid comes at all. Treat an en bloc as a possible bonus, not the plan. If your retirement or next move depends on it, model what happens if it never arrives.
Check your own estate with the En Bloc Readiness Check, or see what the 2026 en bloc changes do and do not fix.
FAQ: Braddell View, Lakeview, and Thomson Reserve
Is Braddell View a good buy in 2026?+ Read →− Hide
Will Braddell View go en bloc?+ Read →− Hide
What did Thomson View sellers actually receive after the en bloc?+ Read →− Hide
What is Thomson Reserve's expected launch price?+ Read →− Hide
What does lease decay mean for Braddell View buyers and sellers?+ Read →− Hide
Should I sell before Thomson Reserve launches or wait?+ Read →− Hide
Your situation is different. Get it in writing.
I'll work through your budget, loan, options and exit in a free written Property Decision Review. No obligation.
Get my free Property Decision Review →Sources+ Show →− Hide
- EdgeProp Singapore: Braddell View avg $1,041 psf, range $1,001 to $1,108 psf · May 2026
- EdgeProp Singapore: Lakeview Estate avg $1,068 psf, range $991 to $1,164 psf · May 2026
- EdgeProp Singapore: JadeScape average $2,296 psf, yield 3.2% · Bishan Park Condo $1,427 psf, yield 2.8% · May 2026
- GuocoLand and Hong Leong: Springleaf Residence 870 of 941 units (92%) sold at an average $2,175 psf, land cost $905 psf ppr · August 2025
- URA: Thomson View Condominium en bloc, $810M, High Court order 1 July 2025; 255 units; $1,178 psf ppr
- URA GLS Programme: Upper Thomson Road Parcel A, Wee Hur and GSC, $1,062 psf ppr · October 2025; estimated launch January 2027
- Thomson Reserve developers (UOL Group, CapitaLand Development and Singapore Land Group): 1,268 units; showflat preview targeted for October 2026; official pricing at launch
- CPF Board: Ordinary Account accrued interest at 2.5% a year, compounded from the date of withdrawal; refunded to the OA on sale and usable for the next purchase
- MAS / HDB / CPF guidelines: CPF use is pro-rated when the remaining lease doesn't cover the youngest buyer to age 95; bank loan tenure limits for shorter leases
- IRAS: BSD rates 2026; ABSD rates 2026
- Building Maintenance and Strata Management Act (BMSMA): MCST governance, sinking fund requirements
Related reading: This corridor is part of a wider look at HUDC estates and the new en bloc consent rules. See the full list of surviving HUDC estates, the En-Bloc Readiness Score framework, and what past HUDC en bloc payouts actually became when reinvested.
Disclaimer+
This article is for informational and educational purposes only. It does not constitute financial, investment, or legal advice. Property investments involve risk. Past performance is not indicative of future results. Readers should seek independent advice from licensed professionals before making any property or financial decision. James Ong is a licensed real estate salesperson (CEA Reg No. R008385F) with PropNex Realty Pte Ltd and is not a licensed financial adviser.
Member discussion