



Update, 3 October 2026
What's now confirmed, and what earlier buyers here made
- Preview: targeted for 17 October 2026. Prices aren't out yet, so every psf figure on this page is still an estimate.
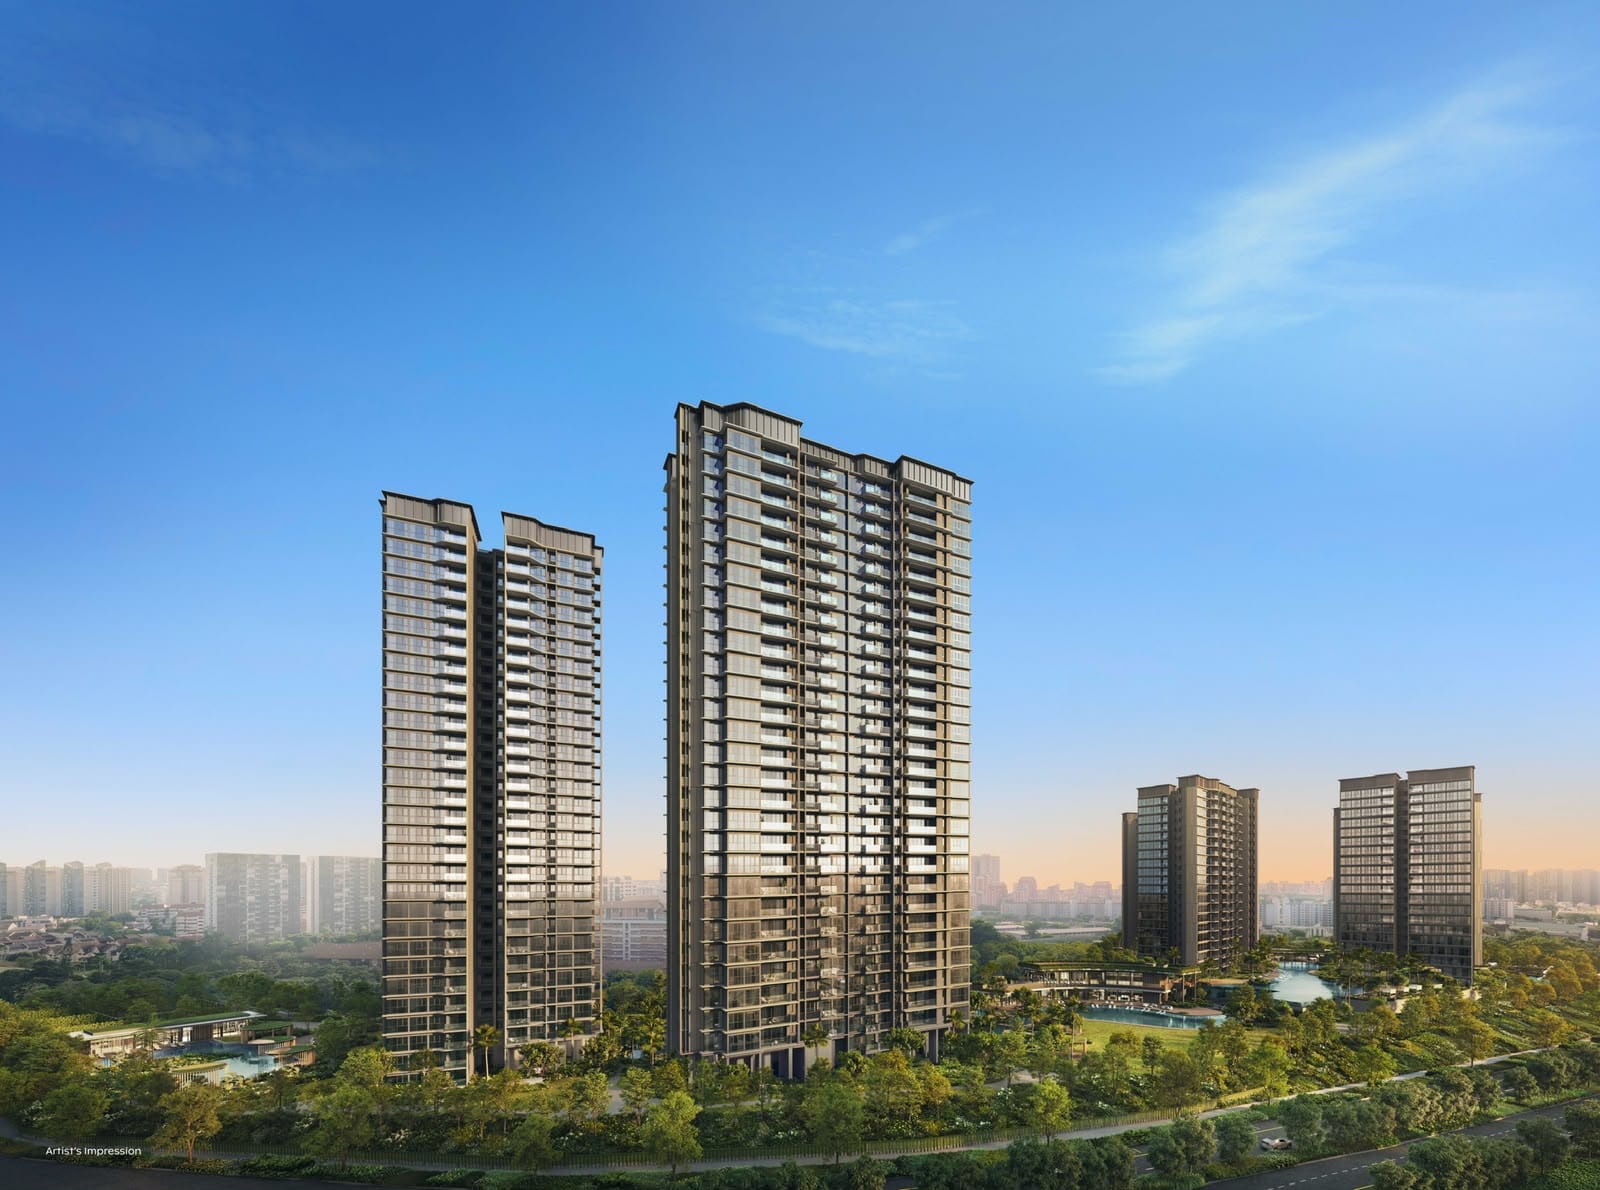
- Size: 1,268 homes in 6 towers (four of 21 storeys, two of 30) on a 51,567 sqm site, about 555,062 sqft.
- Lease and keys: 99 years from 14 July 2026. Expected vacant possession 28 February 2031.
- Homes: 592 sqft to 1,808 sqft. 1,021 car park lots. A sheltered link to Upper Thomson MRT, about 2 minutes on foot by the developer's measure.
The land next door. On 15 September 2026 the Lorong Puntong / Sin Ming Avenue government land sale site, under 500m away, closed with seven bids. Eco World Development topped them at $208.1 million, or $1,612 psf ppr. That is 37% above the $1,178 psf ppr paid for Thomson Reserve's land. It is a small site of about 140 homes, so it says more about what developers will now pay for this location than about new supply.
The record-price question. Six launches on this corridor each opened at a record psf, from Thomson Grand in 2011 to Lentor Modern in 2022. Of the 763 launch buyers who have since sold, 729 sold at a gross gain. Since the Thomson-East Coast Line opened in August 2021, 648 have sold and three made a loss. When they sold mattered more than the record they paid: Thomson Grand sellers before the line opened had 29 losses out of 71, and after it opened, 2 out of 91.
Gains are gross, before stamp duty, fees and financing. Past results don't mean Thomson Reserve will follow. Sources: Thomson Reserve developer e-book V5 (Tamarind Development Pte Ltd: UOL Group, Singapore Land Group and CapitaLand Development); analysis of URA caveats to 30 June 2026 by Stella Thio, PropNex Realty; URA tender results for Lorong Puntong / Sin Ming Avenue, 15 September 2026, as reported by 99.co and Stacked Homes.
Updated 3 October 2026. Confirmed project facts from the developer's e-book added, plus a record of what earlier launch buyers on this corridor made when they sold.
Who This Article Is For
Your HDB flat is worth over a million dollars, 30 years of equity. Thomson Reserve is opening, and something is telling you to look. The brochure shows the psf, the school zone, the MRT distance. What it won't show you: the strata governance, the sinking fund position, and the management council that will run this building for the next 20 years of your retirement. This is the analysis that covers all seven layers. For a buyer who cannot afford to get the last move wrong.
Also relevant: investors evaluating the PSF case · HDB upgraders approaching MOP · Parents co-buying with a child
Deciding between buying now or waiting 18 to 24 months for Parcel A? Read the honest answer →
The transaction-first property industry will tell you Thomson Reserve is a corridor play. Buy the infrastructure thesis, hold for the CRL, exit at a profit. That's not wrong, but it's the investor's question, not the right-sizer's. The one that actually matters here is can you comfortably hold this property through an interest rate cycle, a retrenchment, or the retirement transition, without it becoming the problem? That's the category this series is built around. Starting with the two-minute check above, before the psf breakdown, before the floor plan, before any of it.
Buy at 17 October 2026 preview if you're right-sizing for a 15 to 20 year hold, or co-buying with a child. Wait and model Parcel A only if you're a pure investor who can absorb an 18 to 24 month delay.
Est. launch $2,5XX to $3,1XX psf. Waiting for Parcel A likely costs ~$308,000 more on a 1,100 sqft 3BR by 2030 (full math in Move 3 below).
🌟 STAR Scorecard, Thomson Reserve · District 20 · 2026
Thomson Reserve
James's professional assessment · Not investment advice
S, Schools · 15% 5/5 → 15 pts + Read →− Hide
T, Transport + Transformation · 35% 5/5 → 35 pts + Read →− Hide
A, Amenities · 20% 4/5 → 16 pts + Read →− Hide
R, Returns · 30% 4/5 → 17 pts + Read →− Hide
Score: S(15%)×5 + T(35%)×5 + A(20%)×4 + R(30%)×4 = 83/100 · James's professional assessment · Not investment advice
⚠ James's Warning, Read This Before the Score
That 83/100 assumes the MCST that forms after TOP is a competent one. It usually isn't guaranteed. At 1,268 units, governance quality in the first two AGMs is the single biggest swing factor on whether this score holds up at year 10 or gets discounted by a resident base that never organised itself properly. I've watched both outcomes play out across developments in this price band. The score is only half the analysis. The other half is in Part 7: The Management Reality, or WhatsApp me directly and I'll walk you through what to watch for.
Complete Analysis
7-Layer Analysis: Thomson Reserve
"The analysis every buyer needs. The layer every agent skips."
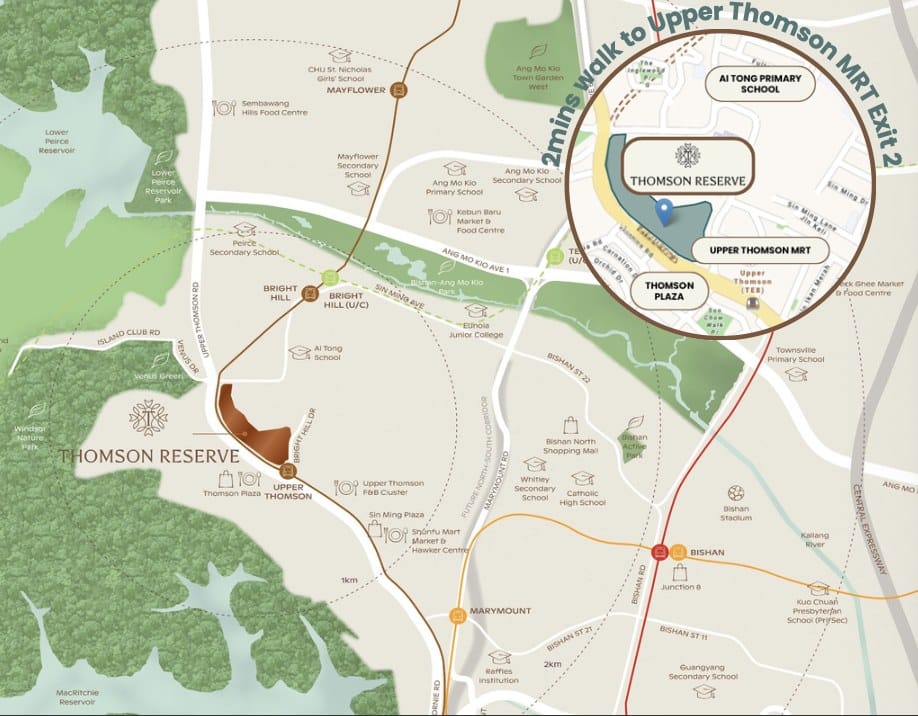
Thomson Reserve corridor, TEL spine, NSC alignment, Ai Tong School zone, and comparable resale projects. School zone distances approximate. Verify stack via MOE Phase 2C tool before OTP.
Development Facts
Verified against Tamarind Development's official Thomson Reserve project fact sheet.
| Address | 1, 3, 5, 7, 9, 11 Bright Hill Drive |
|---|---|
| Blocks | 2 blocks of 30 storeys + 4 blocks of 21 storeys: 6 blocks, 1,268 units, 1 basement + 1-storey carpark |
| Carpark Lots | 1,014 lots |
| Developer | Tamarind Development Pte Ltd, a joint venture of UOL Group Limited, Singapore Land Group Limited and CapitaLand Development Pte Ltd |
| Architect | P&T Consultants |
| Landscape Architect | Eco Plan Asia Pte Ltd |
| Interior Design | 2nd Edition Pte Ltd |
| Main Contractor | Lian Beng Construction |
Unit Mix
Source: Tamarind Development Pte Ltd, official Thomson Reserve project fact sheet.
Helping You Make Better Property Decisions
The Four Risks Most Buyers Never Check Before Signing
Hedge Against Inflation
+ Read →− Hide
Hedge Against Retirement Inadequacy
+ Read →− Hide
Hedge Against Legacy Failure
+ Read →− Hide
The Risk Most Advisers Never Name
+ Read →− Hide
Move 1: What the Market Is Telling YouWhy 17 Years Makes This Different+ Read →− Collapse
The former Thomson View Condominium tried to sell en bloc in 2007, 2011, 2013, 2018, and 2022. Five attempts, four failures. Owners anchored at $950 million. The market refused. On 1 July 2025, Justice Audrey Lim granted the sale order at $810 million. What the owners gave up in headline price, $140 million below their peak anchor. They recovered in certainty. And what the site gained in those 17 years of waiting was three infrastructure confirmations that nobody could have priced in 2007: the TEL, the NSC, and the CRL interchange at Bright Hill.
UOL, SingLand and CapitaLand paid $810 million, or $1,178 psf ppr, the highest D20 residential land price on record. That isn't speculation. It's three of Singapore's most experienced developers committing to a site with a working TEL line, JadeScape's seven-year sales record two streets away, and a confirmed CRL interchange at Bright Hill from 2030. The full land cost analysis, and what it means for your downside, is in Part 1: The Price Floor. The complete GLS pipeline for this corridor and every comparable site awarded between 2021 and 2026 is tracked at the GLS Tracker.
The JadeScape Blueprint: and Why It Underestimates Thomson Reserve
JadeScape is the closest comparable in D20. Launched at ~$1,700 psf in 2018. Transacts today at $2,300 to $2,400 psf. Approximately 40% in seven years. The buyers who entered at launch did so before the TEL was confirmed at Bright Hill, before the NSC was scoped, and before the CRL was announced. They got all three. Thomson Reserve buyers in 2026 have all three confirmed, dated, and partially operational before they sign the OTP.
Sources: URA REALIS, EdgeProp, PropNex Research, June 2026. Thomson Reserve PSF is analyst estimate pending official launch.
Thomson Three. Sitting 200m from Thomson Reserve on the same street. Launched at ~$1,300 psf in 2013 and now transacts at ~$2,080 psf. Buyers who entered then have gained approximately 60% in psf terms before rental income. They did it on a development with no TEL, no NSC, and no CRL. The corridor has repriced three times since then. Thomson Reserve enters after all three catalysts are confirmed. For a right-sizer doing one final move, that sequencing matters more than the launch psf headline. The Thomson Three 2026 analysis has the resale data in full.
The School Zone: Three Things Buyers Miss Before Signing
Ai Tong is one of Singapore's most competitive SAP primary schools, with a DSA pathway to Raffles Institution. Phase 2C(S) priority for families within 1km is the decisive advantage in a ballot that regularly exhausts 1km allocation.
Three checks that most buyers skip. First: verify at stack level. The 1km boundary is measured from each block's building outline to the school gate. Not from the development's postcode. In a 6-tower, 555,062 sqft site, not every block qualifies. Verify your specific unit via the MOE tool before OTP. Second: count the 30-month residency requirement. You must have lived in the property for 30 continuous months before your child's P1 registration date. For a 2026 purchase with a 2030 TOP, plan the birth year accordingly. Third: the 1km boundary gives priority in the ballot. It does not guarantee a place.
Retirement Planning, PS1
For a right-sizer who no longer has school-age children: the school zone is not relevant to your daily life. But it is highly relevant to your resale value. Ai Tong 1km is a permanent demand anchor that brings family buyers back into this corridor every year, independent of market cycles. The capital preservation argument for Thomson Reserve rests partly on this anchor. A building that families want to live in for school reasons is a building with a floor under its resale value that most investment-grade condos do not have.
Legacy Planning, PS2
For a parent co-buying with a child who has young children or plans to: the 30-month residency requirement and the stack-level 1km check need to be done before the OTP, not after. A co-purchase that does not serve the school zone purpose it was partly structured around has reduced its own justification. James verifies stack-level school zone status for every co-purchase client before the price list is released.
Move 2: What the Market Isn't Telling YouThe Layer Every Agent Skips+ Read →− Collapse
Every comparables table you will see for Thomson Reserve shows psf against JadeScape, AMO, and Springleaf. None of them show the one thing that determines whether a right-sizer's retirement capital holds its value through a 15 to 20 year hold: the governance quality of the building you are moving into.
There is a conversation that happens at every AGM in Singapore's ageing mid-range condos that never makes it into any property article. It goes roughly like this: the managing agent presents the sinking fund balance, a council member notes that the waterproofing was deferred again, someone asks why the lift upgrading quote has tripled since last year, and the answer is always the same. The fund doesn't have enough, and the previous council decided to wait. This is not a rare edge case. It is the standard trajectory for a 99-year leasehold development between year 8 and year 15.
Thomson Reserve starts from zero: a fresh sinking fund, a fresh 99-year lease and a new management council set up under the developer before the first owners' AGM. No inherited liabilities and no deferred works from a previous cycle. The new-build premium in 2026 buys you out of that first big maintenance bill, which is arriving right now at comparable D20 resale condos such as Braddell View and the older blocks along Upper Thomson Road. The Braddell View vs Lakeview analysis shows exactly what that deferred maintenance trap looks like in a live development.
The specific risk to watch at Thomson Reserve is the inverse: scale. A 1,268-unit development has a management council of up to 14 members, AGMs with potentially hundreds of proxy votes, and a developer who will step back from governance within three to five years of TOP. The transition from developer-era management to full resident self-governance is where large developments either build a functioning MCST or drift into factionalism. For a right-sizer who plans to live here from TOP in 2030 through to their late 70s, the governance quality in years 5 to 15 is not a secondary consideration. It is the primary consideration. The sinking fund trajectory, the DLP defect pattern, and the managing agent quality signals are what Part 7: The Management Reality maps in full.
Retirement Planning, PS1: The MCST Question Most Right-Sizers Never Ask
Before committing retirement capital to any strata development, ask three questions the brochure will never answer: What is the sinking fund contribution rate, and is it adequate for a development of this size and facility complexity? What does the developer's MCST track record look like at their comparable completed projects? Who is the appointed managing agent, and what is their governance track record? James runs this check as part of every retirement-planning property review. It takes an hour. It is worth more than any psf comparison table.
Pros and Cons+ Read →− Collapse
What's Confirmed
- TEL, NSC and CRL 2030 all confirmed: strongest infrastructure case in D20 2026
- GFA harmonised: 100% liveable sqft, first harmonised project in D20
- Ai Tong School ~1km: permanent demand anchor protecting resale value across cycles
- MacRitchie Reservoir adjacency: permanently protected, views cannot be built out in year 20 or year 50
- Fresh 99-year lease and clean sinking fund: no inherited governance liabilities
- UOL, SingLand and CapitaLand: Singapore's strongest developer consortium, proven pricing discipline
- Raised ground, so reservoir-facing units look down over the tree canopy, a rare feature at this price
What You Need to Verify Before You Sign
- 1,268 units TOPping simultaneously in 2030: resale and rental pool crowded at the same moment
- No integrated mall on site: Parcel A will have commercial ground floor; Thomson Reserve doesn't
- 20% ABSD on a second property, $360K+ on a $1.8M unit before renovation
- Estimated gross yield 2.6% to 3.2%. Not a yield play; the case is capital growth and family living
- Ai Tong 1km is stack-dependent: not all 6 blocks qualify; due diligence required at unit level
- CRL interchange not operational until 2030: part of the infrastructure premium is forward-dated
- A large MCST: 1,268 units need consistently good governance, and the handover from the developer-era council is the key risk
Would You Rather: Thomson Reserve or Stay in D20 Resale?
Thomson Reserve, Oct 2026
- Clean sinking fund from day one
- Fresh 99-year lease: CPF fundable for two generations
- Three confirmed infrastructure catalysts not yet fully priced
- School anchor protects resale floor across cycles
- Reservoir view cannot be blocked in year 20 or year 50
- Governance reset: no inherited MCST liabilities
Stay in D20 Resale, JadeScape / Thomson Three / AMO
- Already own and lease is long enough for your horizon
- Sinking fund verified healthy at recent AGM
- Cannot absorb ABSD on simultaneous purchase
- Entry quantum at new launch exceeds your ceiling
The cost of staying in a 10-year-old D20 resale on a shrinking lease is not abstract. Thomson Three at ~$2,080 psf has 83 years of lease remaining at time of writing. Still long enough. But at year 20 of Thomson Reserve's life (2050), Thomson Reserve has 79 years remaining on a fresh lease, while Thomson Three has 63 years remaining on its 1996 lease. For a right-sizer planning a 20-year hold, that lease differential matters both for CPF usage and for the next buyer's financing options at resale. On the Upper Thomson corridor, the full freehold and leasehold comparison is in the Upper Thomson condos guide.
Move 3: Why Oct 2026 Is a Decision Point+ Read →− Collapse
01, The Right-Sizer's Window Is Closing
Singapore's re-employment and retirement ages rise from 1 July 2026, with the retirement age going to 64 (CPF Board), and CPF LIFE payouts start at 65. For a right-sizer aged 55 to 62, the 2026 preview is worth looking at closely: it comes before the NSC opens in 2027 and before the CRL adds the Bright Hill interchange in 2030. Every year in a home that's bigger than you need carries a maintenance cost and an opportunity cost. On a 5-room HDB with $1.1M of equity, that idle capital is very real.02, NSC Opens 2027, Is It Priced In Yet?
The NSC Lentor viaduct opens in 2027 and will cut the commute to the CBD from Upper Thomson. Buyers at the 2026 preview enter before it opens; how much of that is already in the launch price is the question to test. JadeScape buyers in 2018 went in before the TEL was running, and Thomson Reserve buyers in 2026 go in before the NSC is. Springleaf sold 92% in 48 hours at $2,175 psf. In my view, Thomson Reserve's fundamentals are at least as strong, with a clearer infrastructure date ahead of it, though past gains don't guarantee future ones.03, Legacy Window: Fresh Lease, ABSD Remission Timing
For a parent buying with a child, ABSD remission doesn't apply. It's only for married couples (with at least one Singapore citizen) who sell their first home within 6 months of buying. A fresh 99-year lease helps here, because the property still has plenty of CPF-eligible lease years when the child later decouples, typically 5 to 7 years on. As an illustration only: at $2,800 psf on a 1,100 sqft 3BR, a 10% rise to $3,080 psf by 2030 would add $308,000, before any CRL effect. The co-purchase mechanics are in the ABSD guide.James's Note · CEA R008385F · PropNex Realty
On the Last Move: and What Most Right-Sizers Get WrongMost right-sizers I speak to spend their energy on the psf comparison and the unit type. Those are important. But they are not the question that keeps you up at night in year 12 of a 15-year retirement hold. The question that keeps you up is: did I buy into a well-run building, or did I inherit someone else's deferred maintenance problem? + Read James's Full Note →− Collapse
Who should skip this
Thomson Reserve probably isn't for you if:
- You need rent to cover the mortgage. Gross yield is estimated at 2.6% to 3.2%, so this is a family home and a growth hold, not an income play.
- You plan to sell soon after TOP. About 1,268 units complete together around 2030, so early resale competition will be heavy.
- You want a proven MCST. At this size, the first two AGMs decide a lot, and there is no track record yet.
- You are buying for Ai Tong School without checking your exact stack with MOE's distance tool first.
Prices are still estimates until the official price list is out. Run your numbers on the real figures before you commit.
FAQ: Thomson Reserve 2026
Is Thomson Reserve a good option for right-sizing from an HDB in 2026? + Read →− Hide
For a right-sizer with $1M+ in HDB equity, Thomson Reserve is one of the most structurally sound options in D20 in 2026. The case rests on four things: a fresh 99-year lease with no inherited governance liabilities, a confirmed infrastructure spine that is still being priced in, a school anchor (Ai Tong) that protects resale value across market cycles, and a developer consortium with proven pricing discipline. The specific question is whether the entry quantum works with your CPF, cash position, and retirement timeline, James maps this before any showflat visit. WhatsApp him your numbers and he'll give you a straight answer on whether the quantum works, not just whether the unit looks good.
Can I use CPF to buy Thomson Reserve as a right-sizer? + Read →− Hide
Yes, subject to the Valuation Limit and the remaining lease covering the youngest buyer to age 95. Thomson Reserve's fresh 99-year lease means full CPF usage is available without restriction for any buyer under 66 at time of purchase. For buyers aged 55+, the CPF withdrawal rules change once the Retirement Account is created. The OA balance above the Basic Retirement Sum is available for property purchase. James maps your specific CPF position as part of every retirement-planning property review. Speak to a licensed financial adviser for advice on your overall CPF and retirement plan.
What does Thomson Reserve's MCST governance look like from day one? + Read →− Hide
Thomson Reserve will be run under the BMSMA from TOP. As a new development, its sinking fund starts at zero with nothing inherited, a much better starting point than any D20 resale condo. The specific governance risks at 1,268-unit scale, including the developer handover around years 3 to 5, whether the sinking fund is adequate, and signs of managing agent quality, are covered in full in Part 7: The Management Reality. This is the layer most agents skip, and the one that matters most for a right-sizer on a 15 to 20 year hold.
How does Thomson Reserve work as a co-purchase with my child? + Read →− Hide
A parent co-purchasing Thomson Reserve with a child is a PS2 (Legacy Planning) structure. The key variables: ABSD of 20% applies on a second property for Singapore Citizens; ABSD remission is only for married couples who sell their first home within 6 months, so it does not cover a parent and child buying together; the fresh 99-year lease means CPF can fund the purchase across both generations; and decoupling at a later date (when the child can buy out the parent's share) is structurally cleaner on a harmonised project with an unambiguous liveable area. The ABSD mechanics and co-purchase structure options are in the second property ABSD guide. Speak to a licensed financial adviser for advice specific to your situation.
Should I buy Thomson Reserve or wait for Parcel A on Upper Thomson Road? + Read →− Hide
For right-sizers and families with school-age children: Thomson Reserve now. The school zone, the governance reset from a fresh MCST, and the 2026 entry price before NSC reprices the corridor all point to moving at preview. For pure investors who can absorb 18 to 24 months: model Parcel A first. Parcel A will likely launch at $2,900 to $3,200 psf based on current land cost trends. On a 1,200 sqft unit, a $200 psf gap is $240,000. The gap if both estimates hold. The Thomson Reserve vs Parcel A analysis is in the full corridor comparison. If you're weighing the two, WhatsApp James your profile and timeline and he'll work through both scenarios with you.
What is the retirement income potential of Thomson Reserve? + Read →− Hide
Thomson Reserve's gross rental yield is estimated at 2.6 to 3.2% based on current Upper Thomson corridor rental data and the est. launch PSF range. On a 2BR unit purchased at $1.9M, that translates to approximately $4,100 to $5,000 per month in rental income. Which, combined with CPF LIFE payouts from age 65, contributes meaningfully toward the $550K to $1.3M retirement nest egg DBS recommends (DBS, June 2024). For detailed rental mechanics and what the corridor actually achieves at unit level, see Part 4: The Yield Reality. Speak to a licensed financial adviser before making any decisions based on projected rental income.
Before You Register
You now know more than most buyers walking into this showflat. Three things still decide whether it works for you.
Have you verified Ai Tong's 1km status for your block, not just the postcode? Not every block qualifies.
A fresh sinking fund is only an advantage if the first two AGMs elect a council that knows how to run one. See Part 7 for what to watch for.
Can you comfortably hold through a rate cycle, a job change or retirement, not just through a good market?
These three are what James maps in the pre-launch session below. Not a generic price-list handout.
Is this project right for you?
Every buyer's numbers are different. I'll check your budget, loan, the alternatives and your exit in a free written Property Decision Review. No obligation.
Get my free Property Decision Review →Sources + Show all 16 →− Hide
- URA REALIS: District 20 resale transactions 2024 to 2026, accessed June 2026
- High Court Singapore: Thomson View sale order $810M, Justice Audrey Lim, 1 July 2025
- PropNex Research: Q1 to Q2 2026 new launch sales, RCR median PSF, June 2026
- URA GLS Programme: 2H2026 confirmed sites, 3 June 2026
- URA Master Plan 2019: Bright Hill Drive zoning, MacRitchie Reservoir protection status
- LTA: TEL operational data, Bright Hill CRL interchange confirmed 2030, NSC viaduct from 2027
- EdgeProp Singapore: JadeScape resale PSF $2,300 to $2,400, Thomson Three ~$2,080 psf, May-June 2026
- Business Times: Thomson Plaza acquisition $250M, April 2026
- MOE Singapore: Primary 1 Phase 2C(S) distance guidelines, 2025
- URA: GFA Harmonisation Circular, effective 1 September 2022
- DOS, Population Trends 2025: 18.8% of residents aged 65+
- DBS, "Life After Work" Financial Health Series: $550K to $1.3M retirement nest egg, June 2024
- CPF Board: Retirement age rising to 64 from 1 July 2026, CPF LIFE from age 65, November 2025
- UOB Economics & Markets Research: Singapore property price index gains 2020 to 2025, January 2026
- MOM: 14,490 retrenchments in Singapore 2025, SingFinance citing MOM data, 2026
- GuocoLand / EdgeProp: Springleaf Residence 92% sold at $2,175 psf avg, August 2025
Disclaimer+
This article is for informational and educational purposes only. It does not constitute financial, investment, or legal advice. Property investments involve risk. Past performance is not indicative of future results. Readers should seek independent advice from licensed professionals before making any property or financial decision. James Ong is a licensed real estate salesperson (CEA Reg No. R008385F) with PropNex Realty Pte Ltd and is not a licensed financial adviser.
Member discussion