
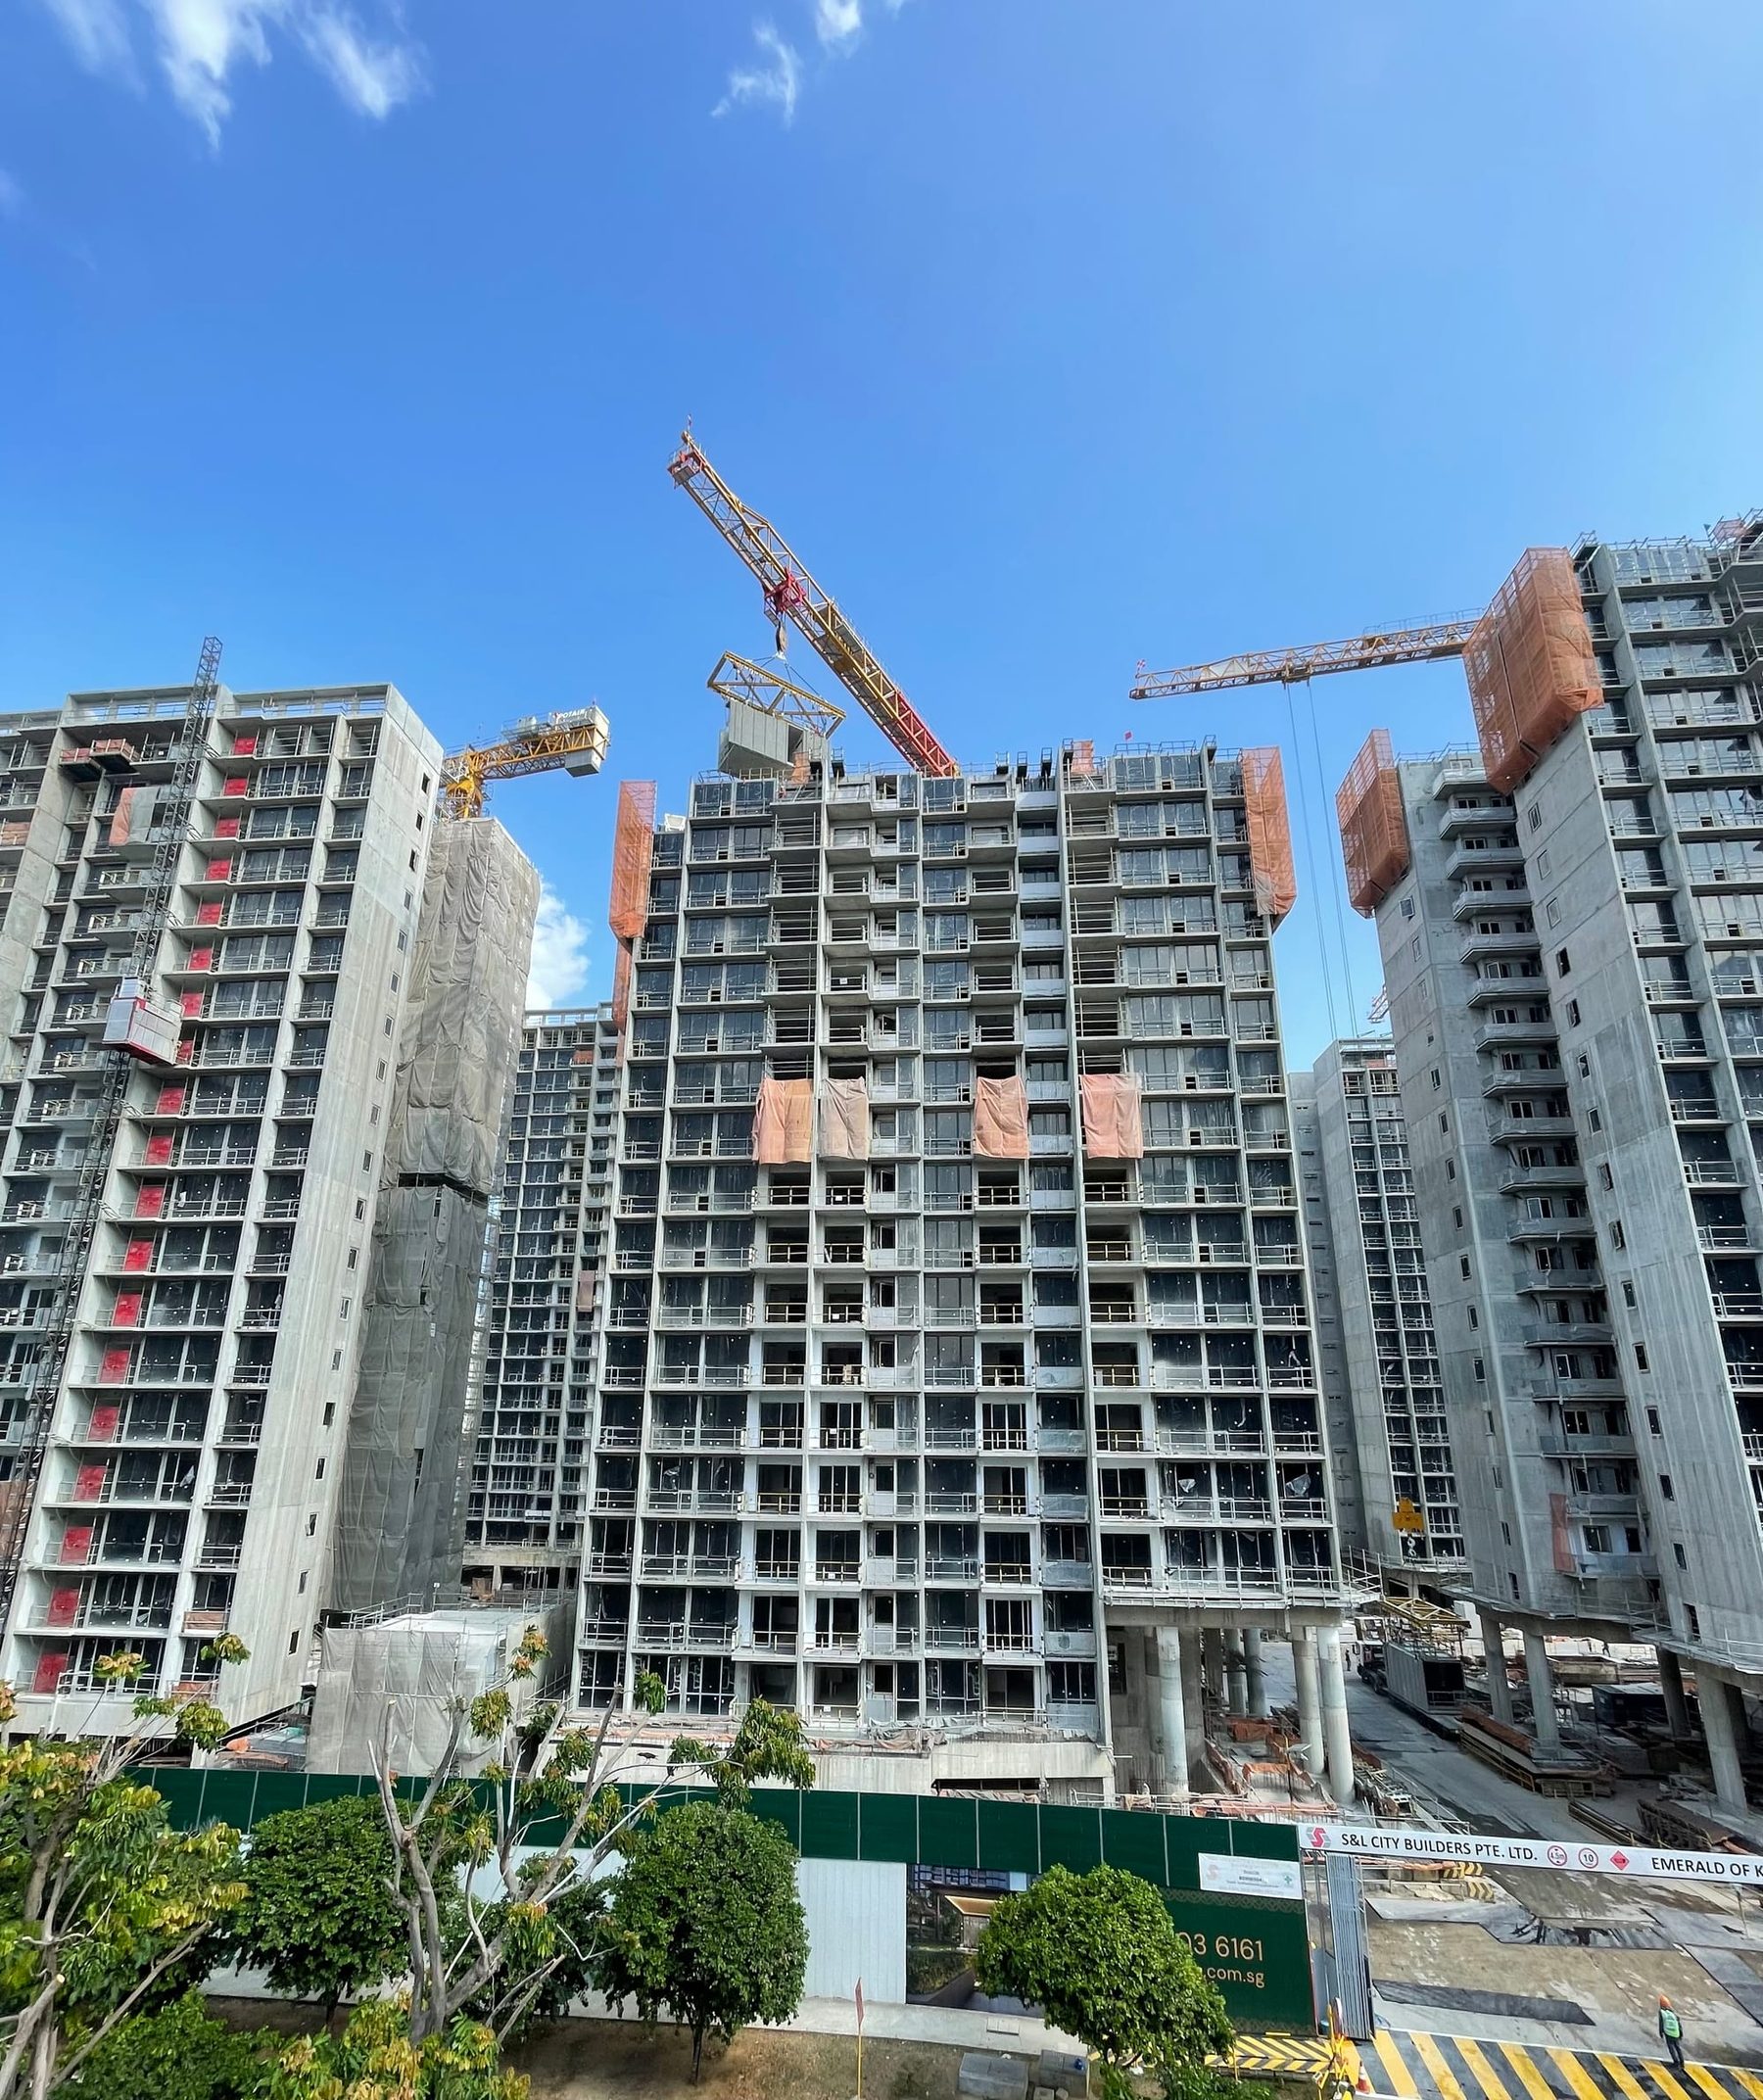



You have researched the psf, measured the MRT distance and checked the school within 1km. That is the research every HDB upgrader does, because it is also the research every developer's marketing is built around. Almost nobody checks the strata governance of the building they are about to live in for the next 15 years.
Short answer: The HDB-to-private upgrade has four steps: confirm your MOP and finances, decide whether to sell first or buy first, run the transaction in the right order, and check the building's management before signing any OTP. Getting the order right avoids unnecessary ABSD. Checking the building decides how the home performs over the next 15 years.
Confirm your MOP and financial position first
The 5-year Minimum Occupation Period runs from the date you collected your keys, not the purchase date (HDB). Before any showflat visit, work out four numbers: your CPF Ordinary Account balance, your outstanding HDB loan, your estimated net sale proceeds after the CPF refund, and how much you can borrow.
The figure that catches most upgraders out is CPF accrued interest. When you sell, the CPF used for the flat must go back to your account with 2.5% a year compounded interest (CPF Board). On a flat bought 8 to 10 years ago, this can add roughly $80,000 to $150,000 to the deductions before any cash reaches you, as an illustration of the scale. Get your actual figure from CPF Board before deciding what you can spend.
- CPF Ordinary Account balance
- Outstanding HDB loan
- CPF used and accrued interest (CPF Board: My Statement, Property)
- Estimated value of your flat
- An In-Principle Approval from your bank, confirming how much you can borrow
Speak to a licensed financial adviser for advice specific to your situation on CPF use, loan structuring and overall financial planning.
Sell first or buy first?
This decision shapes your stamp duty and your negotiating position, so make it before you fall in love with a unit.
| Approach | ABSD | Trade-off |
|---|---|---|
| Sell first | None: you own no other property when you buy | You know your proceeds before committing; you may need to rent in between |
| Buy first | 20% for a Singapore Citizen (30% for a PR), payable upfront | Married couples with a Citizen spouse buying jointly get it refunded if the HDB flat is sold in time |
The refund window is strict: the first home must be sold within 6 months of buying a completed property, or within 6 months of TOP or CSC, whichever is earlier, for a new launch (IRAS). Miss it and the refund is lost. On a $1.5 million purchase that is $300,000, as an illustration of what is at stake. Singles do not qualify for the refund at all.
The transaction, step by step
Get your In-Principle Approval before any showflat visit. It confirms your loan amount and your real borrowing limit under the Total Debt Servicing Ratio (MAS). With it in hand, look only at units within your confirmed budget. In my view, for a first private purchase, Outside Central Region areas with good MRT access tend to offer the best balance of liveability and entry price for someone leaving an HDB flat, though other regions can work if the budget and running costs both add up.
At a new launch, the option fee is typically 5%, with three weeks to exercise. CPF can fund part of the downpayment above the minimum cash portion; confirm the exact amount with your bank and CPF Board first. If you are buying first, track the developer's TOP progress from 12 months out and list your HDB flat three to four months before the expected TOP date.
The building check every upgrade guide skips
Every upgrade guide covers MOP, ABSD, CPF and borrowing limits. What almost none cover is what you inherit when you sign: a strata management structure under the Building Maintenance and Strata Management Act that you will live inside for 10 to 15 years.
For a resale condo, ask for three things before the option period ends: the last three years of AGM minutes, the sinking fund balance against the five-year maintenance plan, and any pending special levy. Recurring disputes, deferred repairs and frequent changes of managing agent in the minutes are worth questioning. If the documents are said to be unavailable, that is useful information in itself.
At a new launch there is no management council yet. The closest guide is the developer's record on comparable completed projects. Once you collect keys, use the defects liability period properly: it runs 12 months, and defects should be reported in writing with photos and a reference number, not by a message on your phone.
Before you sign any OTP
Work out three numbers first: what your flat releases after costs (see the net proceeds calculator), the ABSD you would pay if you buy before selling (see the ABSD guide), and what the loan costs at today's rates (see the mortgage rates guide). If any of the three is a guess, the plan is not ready.
In my view, for most first-time upgraders, selling first is the lower-risk route: no ABSD exposure and full clarity on your proceeds. Buying first makes sense mainly for married couples who can sell inside the refund window and have a specific purchase that needs it.
Questions readers ask
Can I buy a private condo before my HDB MOP is up?
No. You must meet your flat's 5-year Minimum Occupation Period before buying private residential property (HDB). The clock starts from key collection, not from booking. Check your exact MOP date on HDB's portal before planning anything else.
How much ABSD do I pay if I buy before selling my HDB?
As a second property, 20% for a Singapore Citizen and 30% for a PR, payable within 14 days of exercising the OTP (IRAS). A married couple with a Citizen spouse buying jointly gets it refunded automatically if the HDB flat is sold within the 6-month window.
What is CPF accrued interest and how does it affect my budget?
CPF used for your flat must be returned to your CPF account when you sell, with 2.5% a year compounded interest (CPF Board). It comes out of your sale proceeds before any cash reaches you, and on a flat held many years it can run into tens of thousands of dollars.
What is TDSR and how does it limit what I can borrow?
The Total Debt Servicing Ratio caps all your monthly debt repayments, including the new mortgage, at 55% of gross monthly income (MAS). Car loans and other debts count too. An In-Principle Approval with every debt disclosed shows your real limit before you shop.
What documents should I ask for before signing an OTP on a resale condo?
The last three years of AGM minutes, the current sinking fund balance with the five-year maintenance plan, and any pending special levy, all before the option period ends. A legal search will not tell you how well the building is run; the minutes will.
Your situation is different. Get it in writing.
I'll work through your sale price, CPF refund, loan, next purchase and timing in a free written Property Decision Review. No obligation.
Get my free Property Decision Review →Sources
HDB; CPF Board; IRAS, ABSD rates and remission for married couples; MAS, Total Debt Servicing Ratio; Building Maintenance and Strata Management Act.
This article is for informational and educational purposes only. It does not constitute financial, investment, or legal advice. Property investments involve risk. Past performance is not indicative of future results. Readers should seek independent advice from licensed professionals before making any property or financial decision. James Ong is a licensed real estate salesperson (CEA Reg No. R008385F) with PropNex Realty Pte Ltd and is not a licensed financial adviser.
James Ong | CEA Reg No. R008385F | PropNex Realty Pte Ltd
Member discussion